

At some point, you might find yourself short on money with no obvious way to fix it. You’ll have a plan. You’ll have strategies. But you won’t know exactly where the money will come from.
That’s where I am right now. So I tried something that might make some of you groan: I manifested money.
You’ve probably done it too, even if you didn’t call it that. People manifest their destiny all the time by telling themselves what they want or deserve:
I want to be rich.
I want to find a girlfriend or boyfriend.
I want to get married.
I will have two children.
I will make my first million by 35.
I will get into that school.
I will land that hot pre-IPO AI job.
I will write a national bestseller.
I will get promoted to managing director.
I will lose 10 pounds this year and keep it off for the rest of my life.
I will perform in front of a large crowd and make no mistakes.
Some of these come true. Many do not, but they are still worth trying.
So I figured, if people can manifest a spouse or a promotion, why not money? There’s no harm in thinking about money coming to you in the least expected ways.
Before you click away, hear me out. This isn’t my first manifestation rodeo. The last time I did it, I left a finance career six years earlier than planned.
The Liquidity Crunch
I’ve been cash poor lately because of aggressive capital calls. I budgeted for up to $300,000 in capital calls over the first 12 months of a $1 million venture fund commitment. Within six months, $460,000 had been called.
That’s a $160,000 hole, in half the time.
The good news is our passive income still covers all our living expenses. The bad news is that if another capital call hits in the next couple of months, I won’t have the funds.
Manifesting Money In The Hot Tub
One morning I was sitting in the hot tub, thinking about what to write next on Financial Samurai. Out of nowhere I started saying, “Let the money come in unexpected ways.”
I said it a couple of times. Then I went back to scrolling the news on my phone. Very spiritual.
A week later, I went to my PO Box to mail a signed copy of Millionaire Milestones to a consulting client. Every client gets a signed copy of a first print, first edition, which could one day be worth a lot more if you enjoy collecting books. I hadn’t checked my mailbox in three weeks, so mail had piled up.
One envelope was from the tax authorities. That always makes my heart skip a beat.
Money Back From The Government
But this time there was a check inside for $2,799. Yeah baby yeah!
It turns out that on my April 15 extension filing, I reported zero estimated tax payments when I had actually made some. Then when I filed my full return in September, I paid California another $650, based on what the tax software told me to pay. So the Franchise Tax Board sent back money I didn’t know I was owed.
Technically it was my money all along, returned because of my own carelessness. But it felt like free money, and I desperately needed it to rebuild my cash buffer.
It gets better. The federal government apparently owes me a refund too according to a letter they sent, but couldn’t pay it because I’d never added my bank account to my IRS online account. I didn’t even know that option existed. I logged on, added my checking account, and I’m now waiting for another surprise.

The Money Kept Showing Up
The second surprise was consulting demand. I don’t advertise my financial consulting, because demand can be overwhelming and each session takes a lot of work. I prefer about one or two a month.
After the hot tub session, within a week, four people reached out. I said yes to all of them and spaced them out to one per week. That built another 1% buffer for future capital calls.
Although one client still hasn’t paid after nine days. Further, I forgot to ask for a deposit because I confused another deposit for theirs given the sudden flurry of demand. Apparently the universe delivers the leads but not accounts receivable.
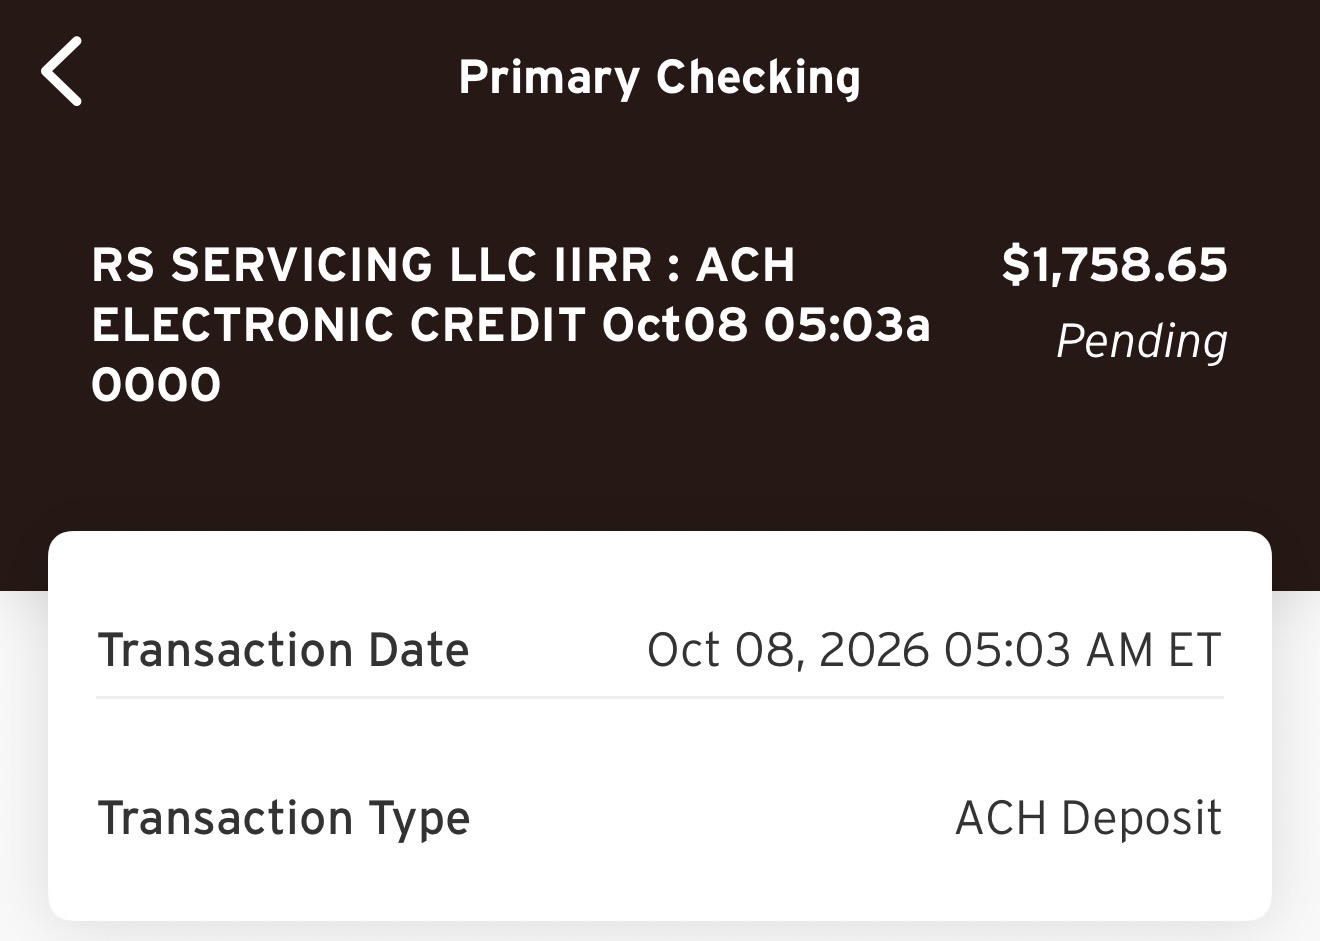
The third surprise was a $1,758.65 distribution from a private real estate fund I invested in almost 10 years ago. The fund has already paid back all my capital and then some, so it’s been off my radar. Out of 17 assets, it has four remaining ones, three of which are performing OK. The last distribution was at least six months ago. $1,758.65 isn’t much, but every dollar counts.
Discovered A Large Underperforming Investment
The fourth surprise was found money of a different kind.
I was going through one of our 40+ financial accounts and noticed an investment that had underperformed for four years. I hadn’t noticed it earlier because it’s held in our corporate account, which my wife mainly overseas.
I didn’t think it would recover in the next 12 months, so I sold it at no capital gain, sad, I know. My original plan was too hold it for 10 years. But that one sale created a buffer for a 13.7% capital call, or $137,000.
I was thrilled because I had not counted this position in my net worth at all. Hooray for having separate accounts and not being able to keep track of everything well.
Old Business Partner Reached Out
The fifth manifestation surprise came from my inbox. The chief marketing officer of a former affiliate partner emailed me out of the blue. We worked together for several years about a decade ago, and then life moved on.
He’s joined a new firm whose product automates banking and bookkeeping for real estate investors. As a landlord who still tracks rent and repairs with a mix of spreadsheets and denial, I get the appeal. It could be a good fit for the Financial Samurai community, but I’ll do my due diligence before saying yes.
Even if nothing comes of it, the lesson stands: relationships you built 10 years ago can still pay off. Treat people well because you never know who’ll come back around.
For perspective, I have not gone prospecting for online business for years. Instead, I just field inbound inquires and decline 99% of them.
All told, I now have about $18,000 in my personal accounts and $137,000 in our corporate account, ready for the next series of capital calls. Any federal tax refund or new partnership income is gravy. That should buy me three to six months of breathing room. Meanwhile, I’ll keep building cash from cash flow.
My First Big Manifest Destiny
This isn’t the first time manifesting has bailed me out.
In 1999, I started my career in New York City. Being at the office by 5:30am was expected. One morning, walking in before sunrise, it hit me: there was no way I could do this for three or four decades.
So I manifested my destiny. I’d be out of finance by 40.
I didn’t just say it once. That goal became the filter for every financial decision I made for the next 13 years. I saved and invested 50% to 80% of my after-tax income and 98% of my bonus every year. The sacrifices required to achieve financial independence no longer felt like restrictions. Instead, every dollar saved felt one step closer to liberation.
When it was finally time to jump, I manifested a solution to the next problem: how to leave without walking away from five years of deferred compensation. Instead of quitting, I negotiated a severance. I kept all my deferred compensation, got a six-figure severance check, and left with a parachute and a buffer.
I left in 2012 at 34. Six years ahead of schedule.
Want To Manifest Your Own Exit?
If you’re thinking about leaving a job you no longer love, don’t quit. Quitting means walking away with nothing. Get laid off with a severance package instead.
I wrote How To Engineer Your Layoff to show you how I negotiated mine, and how you can do the same. You’ll learn how to approach your manager, what you can ask for, and how to leave with a parachute instead of a pink slip and an empty bank account.
Thousands of readers have used it to buy time, a financial buffer, and a fresh start. Use the code “saveten” at checkout to save $10.

What Manifesting Actually Does
Here’s what I’ve learned from both experiences. Manifesting isn’t magic. It’s direction.
Go back to that list at the top. The difference between the ones that come true and the ones that become annual traditions isn’t how often you say them. It’s whether saying them changes what you do the next morning.
When you say out loud what you want, you start noticing things you’d otherwise ignore. The PO Box and gym you’ve been avoiding. The government portal you didn’t know existed. The underperforming position you’ve been too stubborn or too loyal to sell. The consulting requests you’d normally decline.
Every dollar I “manifested” this month was already mine or earned by me. Manifesting just made me go look.
The same was true in 1999. Wanting to retire early didn’t save the money. Saving 50-80% of my income did. But without a clear destiny, I never would have had the discipline to keep doing it for 13 years.
Manifest Your Own Good Life
So what does a good life actually look like to you?
Once you’ve got a good idea, here’s how to make manifesting do something useful:
- Write it down with a date. “Retire early” is a wish. “Out of finance by 40” is a destiny.
- Give it a saving rate. If your goal doesn’t change how much you save, it’s not a goal. It’s a daydream. Save and invest 50% a year for 10 years and you will be free, guaranteed.
- Go find the money that’s already yours. Check your state’s unclaimed property database, old 401(k)s, forgotten accounts, tax refunds, and investments you’ve been ignoring. You may be richer than you think.
- Say yes to opportunities you’d normally decline. Extra work, a side project, a raise you’ve been too nervous to ask for.
- Manifest the exit, not just the destination. The severance package was the difference between leaving with nothing and leaving with a buffer.
When your back is against the wall, you’ll usually find a way out. Sometimes the solution has been sitting in your mailbox for four weeks.
Now, if I could just manifest four-pack abs, that would be an amazing feat. But you can’t have everything.
Readers, have you ever manifested money or a big life goal into reality, and did it come with a plan or just good vibes? What does a good life look like to you, and what’s the one thing standing between you and it? Have you ever found money that was yours all along?
Subscribe To Financial Samurai
Join 60,000+ readers and sign up for the free Financial Samurai newsletter here. Every week, I share what I’m seeing and doing with my own money, from capital calls to cash buffers.
To get new posts in your inbox as soon as they’re published, ad-free for the first few hours, sign up here.
Money is too important to be left up to pontification. I’ve been writing from firsthand experience since 2009, and I’ll keep sharing the good, the bad, and the occasional tax-refund miracle.